Category

Finance

Category

You wear more than one hat in a family business, and some days it feels like you wear all of them at once. You are making payroll, answering customer calls, dealing with relatives, and trying to plan for growth without upsetting the balance at home. That strain is real. When business money and family dynamics start mixing together, even good decisions can get cloudy. In moments like these, business tax preparation services in Portland can help bring clarity and structure to the financial side of things.

Growth is where that pressure often shows up first. More revenue sounds simple until it means hiring relatives, setting pay fairly, tracking loans from family members, and deciding who has authority to spend, sign, or approve. This is where How Accountants Support Family Owned Businesses With Growth becomes more than a nice idea. It becomes a way to protect both the company and the relationships behind it.

Family firms are a major part of the economy. The U.S. Small Business Administration Office of Advocacy outlines the characteristics and economic role of family owned businesses, and the picture is clear. These businesses are common, influential, and often built to last. They also face pressures that nonfamily companies do not. A skilled accountant helps turn those pressures into systems, numbers, and decisions you can actually use.

Family business growth gets harder when roles and money stay unclear

A family business can run for years on trust, habit, and verbal agreements. Then growth exposes every weak spot. One sibling believes profits should stay in the business. Another wants higher distributions. A parent still approves every expense, even though the next generation is supposed to be taking over. Nobody is trying to cause harm, but the lack of structure creates it anyway.

This is where accountants help in a practical way. They do not just prepare reports. They create clean financial records, define how money moves through the company, and show what the business can actually afford. If you are opening a second location, adding inventory, or bringing in another family member, you need more than instinct. You need numbers that separate hope from capacity.

The SBA has also highlighted common challenges family owned businesses face, including succession, conflict, and balancing family needs with business needs. Those problems often look emotional on the surface, but they usually carry a financial core. Pay, ownership, debt, taxes, and control tend to sit underneath the tension.

An accountant can model different outcomes before you commit. What happens if you raise salaries for three family members this year. What happens if one owner retires and wants a buyout. What happens if the company funds expansion and has a slow quarter right after. Good accounting and consulting work gives you a way to answer those questions before they turn into emergencies.

Business accounting and consulting creates structure without stripping away trust

Many owners resist outside financial guidance because they think it will make the business feel cold or corporate. In reality, structure often preserves trust. When compensation is documented, reimbursements are tracked, and ownership decisions are tied to actual performance, fewer arguments become personal.

Accounting support for family companies often starts with the basics, because basics are where many growth problems begin. The IRS explains how business transactions should be recorded, and that foundation matters. If personal and business spending are mixed together, if loans from relatives are undocumented, or if payroll is inconsistent, growth gets expensive fast. Tax issues, cash flow gaps, and disputes over who paid for what can follow.

Strong records also make it easier to talk about succession. You cannot pass a business to the next generation smoothly if nobody agrees on its value, its liabilities, or its earning power. Accountants help build that picture in a way lenders, tax professionals, and family members can understand.

Professional support reduces risk as a family business expands

Growth usually demands decisions in four areas at once. Cash flow, tax planning, ownership, and operations. If one of those falls behind, the others feel it. A business may look profitable on paper and still run short on cash because distributions are too high. A company may add a relative to payroll out of loyalty, then realize too late that margins cannot support the role.

Family business accounting services help you set guardrails. That can mean monthly reporting, budgeting, forecasting, inventory controls, compensation planning, or support during financing and expansion. The point is not to make every decision for you. The point is to help you make decisions with evidence instead of pressure.

Growth Task Handled Informally Handled With Professional Accounting Support
Paying family members Pay rates vary, roles stay vague, resentment builds Compensation is tied to role, market data, and cash flow
Using business funds Personal and business expenses get mixed Expenses are documented, categorized, and reviewed
Planning expansion Decisions rely on instinct and optimism Forecasts show best case, expected case, and risk points
Succession planning Expectations stay verbal and unclear Valuation, tax impact, and transfer options are mapped out
Resolving disputes Arguments become personal fast Financial data gives everyone a shared reference point

Clear steps help family owned businesses grow with less friction

1. Separate family decisions from business decisions.

Create a habit of discussing ownership, pay, and distributions in scheduled business meetings, not at dinner or during a rushed phone call. Use agendas, written numbers, and documented outcomes. This one change lowers confusion more than most owners expect.

2. Clean up the books before the next growth move.

Do this before hiring, borrowing, expanding, or transferring ownership. Reconcile accounts, document loans, review payroll, and make sure spending is categorized correctly. If your records are messy, every major decision will cost more time and carry more risk.

3. Build a forecast around real pressure points.

Do not settle for a broad annual budget. Model the issues that actually affect family businesses, including owner draws, seasonal revenue, debt payments, tax obligations, and family compensation. A useful forecast should show when cash gets tight, not just when sales look strong.

Steady accounting support helps protect both the business and the family

You do not need to choose between growth and peace at home. You do need systems that can carry both. When the financial side of the business is clear, the personal side has more room to breathe. People know what is fair, what is possible, and what needs to wait.

Business accounting and consulting gives family owned businesses a clearer path forward, especially when growth starts putting pressure on roles, money, and long term plans. If you are ready to reduce confusion, strengthen your numbers, and grow with more confidence, now is the time to get support.
As your startup begins to grow, your accounting needs as a small business will grow alongside it. But if you haven’t invested in keeping your financial records and accounting processes up-to-date, you could struggle to find investors willing to fund your company as it continues to expand.

Working with a small business accounting firm in Miami is the quickest and most effective way to help you deal with the many unique accounting challenges faced by smaller companies, and maintain accurate financial records, all year round.

From limited financial resources and a lack of financial infrastructure, to huge cashflow constraints, running a small business is tough, but without professional accounting, your small business may never reach its full potential.

Below are the main benefits of professional accounting for small businesses, many of which will help you provide potential investors with a clearer picture of your startups finances:

  • Better tracking of expenses and income

For tax purposes, accurate and up-to-date income and expenses tracking is essential, without which, you may end up paying more in taxes, or facing non-compliance penalties from the IRS. Even investors will want to see that you’re able to manage your taxes without incurring penalties that could damage your bottom line.

  • Clearer picture of company finances

With professional analysis of financial statements, you can sit down with your accountant and determine exactly how much money is available to you, how much you owe to others, and how much others owe you. All of these details are vital for the making of operational decisions that will have an impact on your company’s finances.

  • Analysis-based business decisions

With data given to you by an accountant, you can make business decisions based upon exactly what cash you have, what that cash is doing, and how much cash you have available to work with.

  • Audit preparation

Audits aren’t fun for anyone, but with financial records that are updated and accurate, you can be much better prepared should they arise, and more importantly, not be hit with penalties for non-compliance.

  • Better management of payroll and employee taxes

For startups with staff, you may find it useful to have your accountant handle the payroll function. They can also help you to set up a proper system for payroll, calculate taxes for payroll, and prepare payroll taxes for filing.

When should startups start working with a professional accountant?

For any startup that wants to grow, or is already growing, working with a professional tax services in Miami can prove highly beneficial. As can working with one when your financial admin increases, your books aren’t properly balanced, or you don’t have a clear understanding of the businesses financial health.

Startups face a whole host of business-related challenges, and without any investors to help them, some could buckle under the financial pressure and never recover. But by investing in professional accounting services, you can make your new enterprise as appealing to investors as possible, with accurate financial data that offers them a realistic picture of both your current and projected finances.

For dental practice owners, it’s important to understand the nuances associated with forming an S Corporation, as it can mean the difference between getting to keep more of the money that they earn, and paying more in taxes than they need to.

However, it isn’t quite true to say that by forming an S Corporation, dental practices can automatically lower their taxes. As professional accounting services for dentists will tell you, the reality is a little more complex.

Read on to learn how to maximize your savings and grow wealth as the owner of a dental practice S Corporation:

S Corporation basics

As flow-through entities, the profits and losses of S Corporations are passed through to the owner, who reports them on their personal tax return. The owners of S Corps, unlike sole proprietors, are classed as employees of their corporation, allowing part of their income to be taken as W2 wages, as well as distributions.

When managed effectively, this distinction can create a significant tax advantage for dental practice owners.

The important difference between W2 wages and distributions.

W2 wages are subject to Medicare (FICA) and Social Security taxes, which currently totals 15.3% on wages up to $184,500, after which the only applicable portion is Medicare. Distributions, on the other hand, aren’t subject to Medicare, which means that dental practice owners can reduce payroll taxes legitimately, by balancing distributions and wages effectively.

Use of this strategy helps to lower taxes while the practice remains IRS compliant.

What is reasonable compensation?

S Corp owners are required by the IRS to pay themselves an amount deemed reasonable for their work. If they pay themselves too little in W2 wages, an audit might be triggered and distributions may be reclassified as wages, leading to penalties and back taxes.

too little in W2 wages can trigger audits and reclassification of distributions as wages, leading to back taxes and possible penalties.

Here are the reasonable compensation guidelines for dentists:

  • Minimum W2 – for a modest practice, at least a six figure sum
  • Moderate to high-profit practices – W2 should scale with income to stay reasonable
  • Maximum W2 – usually capped at $360,000 for retirement funding purposes

When allocated properly, compliance is assured, savings can be made on taxes, and retirement contributions maximized.

Strategies for retirement plans

Owners of S Corps can fund Profit Sharing, 401(k) Safe Harbor or Defined Benefit plans, but contributions are tied to W2 wages. As W2 wages increase, the higher the permissible level for contributions, and the greater the tax deductions.

The importance of cashflow integration

Every decision made about W2 wages or equipment purchases, can have an impact on cashflow, hence S Corp strategies and tax planning should never be viewed in isolation.

For instance:

  • Investing in new equipment for deductions without properly planning cashflow, can cause problems for the following year
  • When funds are allocated to retirement plans, dental practices must carefully consider their overheads, debts, and personal living expenses.
  • When proper planning is carried out, any excess cash can be made available for the growth of the practice, or for personal pursuits

To get the most out of an S Corp as a dental practice, you should work closely with an experienced firm who provide bookkeeping for dentists in Miami, as well as accounting and tax guidance. They will regularly review your allocations for W2s and distributions, help you to align your retirement contributions with W2 to maximize deductions, and guide you on making equipment purchases so that your needs in terms of cashflow and tax planning, can be met. When carried out effectively and legitimately, S Corp strategies can help dentists save many thousands of dollars every year, accelerate their retirement savings, and give them the financial freedom they’ve worked so hard to achieve.

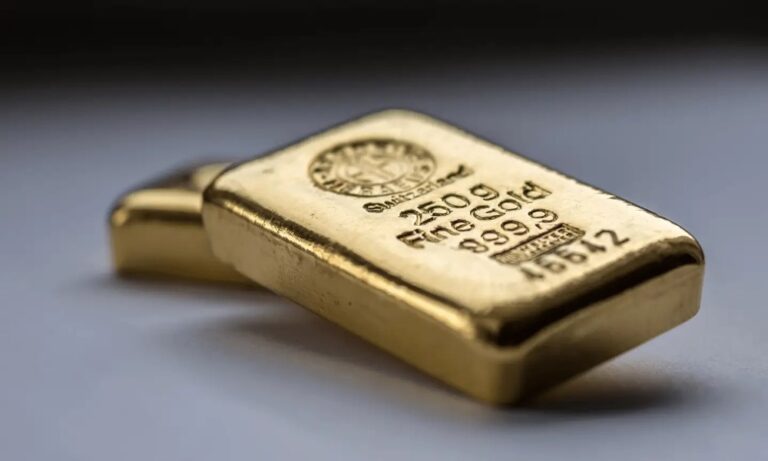
If you’re looking to sell gold bullion Hobart, understanding buy-back policies is essential before making any decisions. These policies determine how easily you can liquidate your gold, how much you’ll be paid, and what conditions apply when you sell. Whether you’re a first-time investor or someone who has held gold for years, knowing the fine print can significantly impact your returns.

At its core, a bullion buy-back policy is a commitment from a dealer or company to repurchase bullion products they have sold, or in some cases, any gold bullion you own. Most reputable dealers offer buy-back services, but the terms can vary widely. Typically, the buy-back price is based on the current spot price of gold, minus a small margin to cover the dealer’s costs and profit.

When planning to sell gold bullion, one of the first things to check is whether the dealer guarantees buy-backs on all products or only on items purchased directly from them. Some dealers prioritize their own minted bars and coins, offering better rates for those compared to third-party products. This distinction can influence how much money you ultimately receive.

Another critical factor is pricing transparency. Reliable bullion dealers clearly display their buy-back rates in real time, often tied to global gold prices. The difference between the buying price and selling price, known as the spread, should be competitive. A tighter spread means you retain more value when selling. If pricing is unclear or requires negotiation, it is often a warning sign.

Documentation requirements also play a role in buy-back policies. Some dealers require proof of purchase, particularly for higher-value transactions. This helps confirm authenticity and ensures compliance with financial regulations. Keeping your receipts and certificates of authenticity is more than just good organization. It can speed up the selling process and prevent delays.

Liquidity is another major benefit of strong buy-back policies. Gold is widely regarded as a liquid asset, but that liquidity depends on how easily you can find a buyer. Established dealers with clear buy-back commitments provide a ready market, allowing you to convert your bullion into cash quickly. This is especially important during economic uncertainty when access to funds becomes a priority.

Fees and additional charges should not be ignored. While many dealers include their fees within the buy-back price, some may charge extra for testing, handling, or administration. Always ask for a complete breakdown so you understand exactly what you will receive. Even small fees can reduce your final payout, particularly when selling larger quantities.

Security and trustworthiness are equally important. When you decide to sell gold bullion Hobart, you are dealing with a valuable asset. Reputable dealers operate from secure premises, use professional testing equipment, and follow strict verification procedures to confirm purity and weight. Checking reviews and credentials can help you avoid scams or unfair practices.

Interestingly, buy-back policies have evolved alongside the precious metals market. In the past, selling gold often involved pawn shops or private negotiations. Today, modern bullion dealers offer streamlined services, including online pricing tools, instant quotes, and courier options for remote sellers. This has made it far easier and more convenient to sell gold than ever before.

In conclusion, understanding bullion buy-back policies is key to protecting your investment and maximizing your returns. From pricing structures and documentation to fees and dealer reliability, each factor plays a role in how smooth and profitable your selling experience will be. Taking the time to research your options ensures that when you are ready to sell, you are in the best possible position.

Finding a lifetime free RuPay credit card that actually delivers value seems challenging when most promotional offers come with hidden conditions. You want the benefits of India’s domestic payment network without paying annual fees that eat into your savings.

The best lifetime free RuPay credit cards in 2025 combine zero annual fees with meaningful rewards, UPI integration, and practical benefits that enhance your daily spending experience without ongoing costs.

Why Choose Lifetime Free RuPay Cards?

  • No Annual Fee Burden: Enjoy credit card benefits permanently without worrying about annual fee renewals, spending targets, or surprise charges that reduce your net savings.
  • UPI Credit Integration: Link free RuPay cards to UPI apps for seamless digital payments while earning rewards on transactions typically limited to bank account balance.
  • Indigenous Network Support: Support India’s domestic payment ecosystem while accessing competitive benefits and features comparable to international card networks.
  • Entry-Level Accessibility: Free RuPay cards often have relaxed eligibility criteria, making them accessible to first-time users and those building credit history.

What Are the Top Lifetime Free RuPay Credit Card Categories?

  • Cashback Focused Cards: Cards offering 1-5% cashback on specific categories like online shopping, groceries, or fuel without annual spending caps or fee obligations.
  • UPI Reward Cards: Specialized cards providing accelerated rewards on UPI transactions, perfect for users who frequently pay through digital payment apps.
  • Student Cards: Designed for college students and young professionals with lifetime free status and benefits tailored to their spending patterns and lifestyle needs.
  • Basic Rewards Cards: Entry-level options offering fundamental reward points on all purchases with simple redemption processes and no complex terms.

What Key Features Should You Look For?

  • UPI Linking Capability: Ensure the card supports UPI integration for maximum payment flexibility and reward earning opportunities across digital transactions.
  • Reasonable Reward Rates: Look for cards offering 1-2% rewards or cashback on regular spending without complicated category restrictions or earning caps.
  • Fuel Benefits: Fuel surcharge waivers of 1% on petrol pump transactions can provide significant savings for regular vehicle users and commuters.
  • Online Shopping Rewards: Accelerated rewards on e-commerce platforms benefit frequent online shoppers who make regular digital purchases throughout the year.

What Are the Eligibility Requirements?

  • Minimum Income: Most free RuPay cards require monthly income between ₹15,000-₹25,000, making them accessible to entry-level professionals and students.
  • Age Criteria: Applicants typically need to be 21-60 years old, with some banks accepting 18+ for student cards with parental guarantors.
  • Documentation: Standard requirements include PAN card, Aadhaar, income proof, and address verification without extensive additional documentation.
  • Credit Score: Many free cards accept applicants with fair credit scores (650+) or no credit history, making them suitable for credit-building purposes.

How Do You Apply for Lifetime Free RuPay Cards?

Online Application: Most banks offer digital applications through websites or mobile apps with instant approval decisions for eligible candidates.

Bank Branch Visit: Traditional application process through bank branches with personal assistance for document verification and query resolution.

Pre-Approved Offers: Check for pre-approved lifetime free card offers from banks where you maintain accounts or have existing relationships.

Agent Assistance: Bank representatives or authorized agents can guide you through the application process and help choose suitable card options.

Conclusion

Lifetime free RuPay credit cards provide excellent value for cost-conscious users who want credit facilities without ongoing fees. Focus on cards offering UPI integration, reasonable rewards, and benefits matching your spending patterns to maximize value from these zero-cost financial tools.