Category

Finance

Category


In India, there are different types of insurance policies that serve different purposes. So, read on to know the must-have insurance policies that can help you secure your finances.

Insurance policies provide financial protection against life uncertainties such as sudden death, accident loss of property, serious illness, etc. However, insurance comes with a cost. And, while you cannot insure everything, there are certain things that you must get covered, especially those that will have a high financial impact on your life and the lives of your dependent family members.

In India, the insurance sector, over the years, has evolved significantly. Today, there are different types of insurance policies that you can consider buying. Right from protecting your home to getting protection against travel mishaps, there is a policy for everyone. So, if you are not sure what insurance to buy? The following types of policies are a must-have for all.

Health Insurance

Life in a city has become extremely stressful, and the pollution levels have increased beyond the safety levels. Also, there has been a steep rise in medical costs. In such a scenario, a health insurance policy is a must-have. It helps you get financial protection against medical emergencies in the family. With a robust healthcare plan, you can have peace of mind knowing that you can provide the best medical care to your beloved without worrying about the high treatment cost.

Experts recommend buying good health insurance with an adequate sum assured to have sufficient coverage for various hospitalisation-related expenses. As there is a myriad of plans available in the market, ensure that you compare the policies carefully and choose the one that offers maximum protection and suits your requirements.

Life Insurance Policy

While a health insurance policy covers the treatment expenses, a life insurance policy helps you secure your family’s financial future in your absence. Today, there are different types of life insurance policies that offer several benefits. There are some plans like the Unit Linked Insurance Plan that gives you the dual advantage of insurance protection and investment.

If you are looking for a simple life insurance policy that provides maximum protection at an affordable cost, it is best to invest in a term life insurance policy. Under this policy, the insurance company pays a lump sum amount to the family in the event of your unfortunate demise before the end of the policy term.

Homeowners Insurance

A home is one of the most valuable assets you may own, and you would surely want to keep it protected from unexpected events like damage due to natural catastrophe, theft, burglary, etc. So, as a homeowner, you must invest in a home insurance policy. It helps you get protection against the damage to the house and the personal belongings you may have inside the home. Additionally, if you wish to avail of a home loan, the lender may require you to purchase a home owner’s insurance before approving the loan.

Cancer Insurance 

Although most health insurance policies will cover the cancer treatment expenses as per the terms and conditions, in most cases, the coverage may not be enough to cover the full cost. Typically, the cancer treatment can go up to 5 lakhs or more, and in such a situation, a standalone cancer policy will be useful to cover the full cost. Typically, in cancer insurance, the insurers pay a lump sum amount as soon as you are diagnosed with the disease. You can use the amount to cover the treatment cost as well as to meet your other expenses.

Motor Insurance

If you own a car or bike, it is mandatory to own a car or bike insurance as per law. Driving without valid insurance can attract a hefty penalty. Apart from complying with the legal requirement, motor insurance is crucial to get protection against the financial losses you may incur if you get involved in an accident. Typically, the insurers in India offer two types of motor insurance – third-party insurance and comprehensive insurance. Make sure that you assess your requirements well and choose the right kind of policy.

Now that you know the must-have insurance policies make sure that you invest in one and get full financial protection against liabilities.


Mutual funds are investment vehicle that are known to offer capital appreciation over the long term. Asset Management companies owning mutual funds collect money from investors sharing a common investment objective and invest this pool of funds across a diversified portfolio of securities and money market instruments. Market regulator SEBI (Securities and Exchange Board of India) describes mutual funds as “a mechanism for pooling the resources by issuing units to the investors and investing funds in securities in accordance with objectives as disclosed in the offer document. Investments in securities are spread across a wide cross-section of industries and sectors and thus the risk is reduced. Diversification reduces the risk because all stocks may not move in the same direction in the same proportion at the same time. Mutual fund issues units to the investors in accordance with the quantum of money invested by them. Investors of mutual funds are known as unitholders“

Some of the major mutual fund categories include equity, debt, solution oriented, hybrid, index, gold, ETF, banking and PSU etc. These are just categories which have been further subcategorized by SEBI for investors to be able to take an informed investment decision. Large cap funds are those mutual funds that predominantly invest in stocks of companies with large market capitalization. These funds are famous among other equity funds because they invest in companies that have a reputation for being financially well established. Large cap funds are also known as bluechip funds. 

The reason several people invest in bluechip funds is because there is very less chance for these funds to underperform even in volatile markets. The fund manager picks stocks that only belong to large cap companies, thus bringing in less volatility to the fund’s overall portfolio. Bluechip funds are professionally managed funds owned by reputed Asset Management Companies. These are actively managed funds that aim to offer capital appreciation to investors over the long term. If you have a short term investment horizon then you should reconsider investing in bluechip funds. Since these are equity oriented schemes, bluechip funds tend to get affected by the daily market vagaries. There is a good chance that your bluechip portfolio may incur losses over the short term. Historically, equity mutual funds have offered decent capital appreciation as compared to other traditional financial instruments. Also, since bluechip funds only invest in stocks of companies with large market capitalization, the investor’s portfolio is less likely to face volatility due to the inclusion of bluechip funds.

If you are seeking long term capital appreciation through investments in bluechip funds, then you can consider starting a SIP. Systematic Investment Plan, abbreviated as SIP, is an easy and hassle-free way to invest in bluechip funds. If you have lumpsum cash at your disposal then you can make a onetime payment towards your bluechip funds. However, with lumpsum investment you end up exposing your entire investment amount to the vagaries of market volatility. If you do not have lumpsum amount at your disposal then you can start a SIP in bluechip funds. With SIP, all you need is to be a KYC compliant individual following which every month on a fixed date a predetermined amount is debited from your savings account and electronically transferred to the bluechip fund. If you are unsure about how much you need to invest at regular intervals to achieve your life’s ultimate goals, then you can refer to an online SIP calculator. SIP also gives investments an opportunity to benefit from power of compounding. Your small investment amounts can multiply and turn into a decent corpus in the long run.

If you are unsure about investing in mutual funds, then it is better to consult a financial advisor.

Corporate bond funds are a such debt fund category generally considered by those mutual fund investors who carry a moderate appetite for risk. That’s because a corporate bond fund allocates at least 80 percent of its total assets in AAA and AA+ rated bonds. Corporate debt funds are sometimes used for rebalancing a mutual fund portfolio especially during the current times of the ongoing global pandemic that has affected the performance of the financial markets and global economies worldwide. Corporate debt funds that invest in lower credit rating bonds generally do so with the hope of seeking higher capital gains. However, such investments may not be able to withstand volatile market conditions and hence investors prefer shifting to corporate debt funds as they invest in AAA and AA+ rated bonds.

How does corporate debt fund generate capital appreciation?

Corporate debt funds work similar to the way lending money in exchange for interest and long term capital appreciation works. A corporate debt fund aims to generate capital appreciation by investing a minimum of 80 percent of its total assets in AAA and AA+ rated bonds and other fixed income securities. These funds aim to generate income and interest on the principal investment amount during the term of the debt fund.
A positive graph in the performance of a corporate bond fund denotes increase the NAV of the fund, thereby generating profits. On the other hand, a decrease in NAV has a negative impact on the portfolio value of the corporate debt fund.

It is the responsibility of the fund manager to craft a feasible investment strategy that will work out in accordance with the investment objective of that debt fund and help it beat its benchmark. These funds generally invest in high credit rated bonds that tend to improve their credit rating over a stipulated time period.

Start a SIP in corporate debt funds
If you wish to achieve success with your corporate debt fund investments, consider starting a SIP. Systematic Investment Plan or SIP is a systematic investment approach towards corporate debt fund investments. Individuals seeking long term capital appreciation through regular, disciplinary investments usually opt for SIP. To start a SIP, all an investor has to do instruct his / her bank, following which every month on a fixed date, a predetermined amount is debited from your savings account and electronically transferred to your corporate debt fund. When the NAV of the fund is low, you are allotted more units and when the NAV is high, a smaller number of units are allotted to investors. This results in the investor benefiting from rupee cost averaging. Also, you may continue investing in corporate debt funds through SIP until your investment objective is met. Those investors who are unsure about how much they need to invest at regular intervals can refer to an online SIP calculator.
Now that you know how corporate funds generate capital appreciation, planning on investing in these debt schemes? Before investing, make sure that you are investing a consistent performing fund that has a proven track record. Check for the fund’s past performance and if possible, compare it to other funds that fall in the same category. Also make sure that the corporate debt fund that you are about to invest in has a feasible expense ratio. A fund with a high expense ratio might affect your capital gains in the long run.

If you are new to mutual funds or financial planning in general, do consult a financial advisor. Also, only invest if the corporate debt fund scheme holds the potential to help you achieve your life’s short term financial goals.

Although there are multiple financial schemes for Indian investors to choose from, these days most investors turn to mutual funds to achieve their lives financial goals. even investors who have been relying on conservative investment avenues and not shifting to Mutual Funds because of their high risk reward ratio and the superior capital appreciation that these market linked schemes are offering. The beauty of mutual fund investments is that investors do not need to have a large sum gum sum surplus cash at their disposal to invest. Thanks to a convenient investment option like a SIP (systematic investment plan) investors can now build wealth over the long-term through systematic and disciplinary investing. 

What is SIP?

Earlier the only way to invest in mutual funds was by making a one time lump sum payment. investors were allotted units in quantum with the investment amount and depending on the fund’s as its existing net asset value (NAV). However lump sum investment has its own downside. When you make a lump sum investment you end up exposing your entire finances to the dangers of equities. We all know that equity markets are volatile in nature and there is a chance of your portfolio in current losses thus affecting your entire investment amount.

Thanks to systematic investment plan investors now have the liberty of making small systematic payments at periodic intervals instead of making a one-time lump sum investment. SIP is an easy and convenient way to invest in mutual funds. If you are a KYC compliant individual, you can invest in mutual funds to escape from the comfort of your home or office using a smartphone or laptop with a decent internet connection. All investors must do is complete a one time and date with their bank following which every month on a fixed at a predetermined amount will be debited from the savings account and electronically transferred to the desired mutual fund. 

SIP for long term goals?

SIP investments are known to offer capital appreciation over the long term. This is the reason why several investors consider starting and mutual fund SIP so that they can target their life’s monetary needs. There are several benefits that investors can avail if they start on a mutual fund SIP. The biggest advantage mutual fund investors have through SIP investments is that their finances stand a chance of benefiting from the power of compounding. the small payments that investors make towards the mutual fund investment, they can multiply over the long term and transform into a large corpus through compounding. In mutual funds, compounding refers to the interest earned from the interest earned from the initial investment amount. Whenever a mutual fund scheme on profits these gains are invested back in the scheme. Over a period, the interest earned on the initial investment keeps on earning interest depending on the market movement. if you have long-term financial goals like building a retirement Corpus for buying a weekend home or if you want to give your daughter at destination weddings or if you want to send children abroad for overseas education and then all these goals can be made through long-term SIP investments. Another advantage of investments is that it allows the appreciation of rupee through rupee cost averaging. when that asset value of a mutual fund is low or more units are allotted to the portfolio. similarly, when the net asset value of a fine is hi lessons are allotted and adjusted depending on the SIP investment amount. This allows for a rupee cost averaging in his known to benefit one’s investments over the long term.

Investments in mutual funds may offer capital appreciation for investors who are expected to consult a financial advisor before investing.

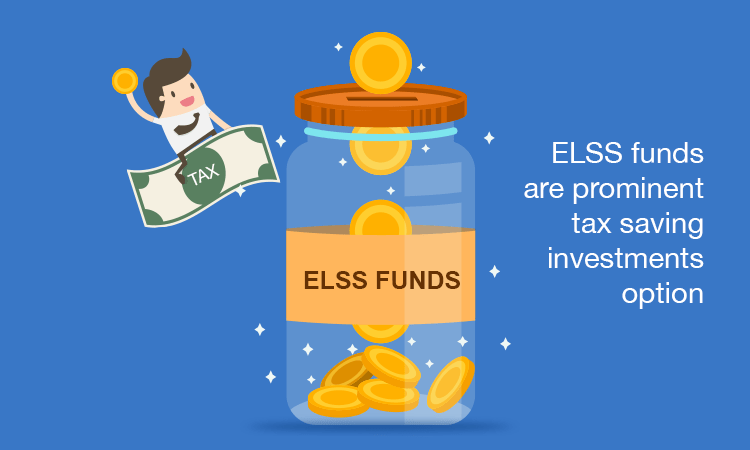
Equity Linked Savings Scheme, widely popular among Indian investors as ELSS is the only mutual fund scheme that comes with a tax benefit. ELSS can be considered as a modern investment tool to save tax and earn capital appreciation over the long term. Earlier, the Indian investors had only conservative tax saving schemes to choose from. These conservative tax saving instruments came with a lengthy lock-in periods. Furthermore, the interest rates that these schemes offered was always on the low end. With such low fixed interest rates, one might fall short of achieving their life’s long term financial goals. But thanks to the introduction of ELSS, investors can now expect high capital appreciation. Also, ELSS comes with a short lock in period. ELSS fund investors cannot redeem or withdraw their funds for a minimum period of 36 months from the date of investments. That’s because ELSS comes with a predetermined lock in period of 3 years. Having said that, this is probably the shortest lock in as compared to other tax saving instruments.

In order to understand how ELSS works here’s an example:

Madhavi Mehta is a data scientist with a gross annual income of Rs. 12.75 lakhs. This lands Madhavi in the 30 percent tax slab. After learning from her HR that she needs to submit tax investment proof, Madhavi decides to invest Rs. 1.5 lakhs in ELSS fund. According to Section 80C of the Indian Income Tax Act, 1961 one can invest up to Rs. 1.5 lakhs in ELSS and claim tax deductions for the same. Thus, by investing in ELSS, Madhavi’s gross taxable income has come down to Rs. 11.25 lakhs. Thanks to ELSS, she was able to bring down her tax liability.

Things to consider before investing in ELSS. Are ELSS risk free?

ELSS is an equity oriented scheme which means the fund predominantly invests (minimum 80 percent) in company stocks and other equity related instruments. Thus, one can say the ELSS is a high risk portfolio carry mutual fund scheme. However, every scheme carries some amount of risk with also. Also, if you are investor with a short term investment horizon then you might be exposing your finances to market’s volatile nature. Mutual funds like equity funds tend to get affected by daily market fluctuations. However, over the long term these investments have shown positive outcome. If you invest in ELSS with a long term investment horizon, not only will you have to not worry about the market vagaries, but your investments might also succeed in overcoming inflation. 

However, before investing in this tax saver fund it is better that you determine your risk appetite. You can even consult a mutual fund expert or a financial advisor who might be able to help you determine whether you hold the appetite for risk for investing in ELSS. There are multiple ways to invest in ELSS. You can either make a onetime lumpsum investment or you can opt for a SIP. A lumpsum investment in ELSS is made by deciding an amount and investing this amount right at the beginning of the investment cycle. SIP (Systematic Investment Plan) on the other hand, gives investors an opportunity to make small investments at regular intervals.  Opting for a SIP in ELSS with a long term investment horizon can even reduce the overall risk of the investment. Every month on a fixed date, a predetermined amount will be debited from the investor’s savings account and electronically transferred to the ELSS fund. This allow minimum exposure to market risk as compared to lumpsum investment.

Although ELSS investments aren’t risk free, they do offer a tax benefit and capital appreciation over the long term.